

Europe’s Solar Procurement Reset: Local Content, Deal-Price Discipline and Merchant Storage
Europe’s Solar Procurement Reset: Local Content, Deal-Price Discipline and Merchant Storage
Solar Hot Topics Report | 11 September 2026 | Beijing Time
One-line takeaway
Europe’s solar opportunity is becoming more conditional: buyers now need traceable local-content evidence, format-specific transaction pricing and proven storage execution, while capital is concentrating around platforms that can convert pipelines into operating assets.
Priority hot topics ranked by sales value
1. A proposed 50% “Made in Europe” threshold could reshape publicly supported solar procurement
Three European Parliament rapporteurs working on the proposed Industrial Accelerator Act have called for the threshold for European-made and low-carbon products in strategic sectors to rise to 50% by 2036. Their draft direction also seeks higher European content in solar panels and tighter component definitions to reduce circumvention. This is not final law, but it is already a procurement-design signal. Suppliers that wait for the legislative process to finish may discover that their bill of materials, origin records and carbon data cannot be assembled quickly enough for public tenders or subsidized projects. The immediate commercial response is to build a product-level evidence pack that distinguishes assembly location from cell, wafer, glass, frame and other component origins.
Event date: 9 September 2026 | Publication date: 9 September 2026 | Priority: Critical | Confidence: High that the proposal exists; medium on final implementation. Source
2. Module offer prices and executable deals are diverging by format, technology and delivery point
SMM’s 10 September assessment describes a market in which higher production costs are supporting manufacturer guidance while weak project economics and uneven demand continue to constrain completed transactions. Conventional TOPCon prices were broadly stable to slightly firmer and high-power offers were unchanged, but premium structure mattered more than the headline move: high-power G12R TOPCon was reported at about a 7% premium to conventional G12R, while selected BC formats carried much wider premiums. In Europe, delayed shipments resumed, but new utility-contract activity remained limited; warehouse pricing in Portugal and Greece was reported roughly 2.2%–2.4% above Rotterdam for comparable formats. The sales implication is to separate list guidance from signed-deal evidence and quote by module format, efficiency class, Incoterm, warehouse location and delivery week.
Event date: 10 September 2026 | Publication date: 10 September 2026 | Priority: Critical | Confidence: Medium-high; individual transactions remain location-specific. Source
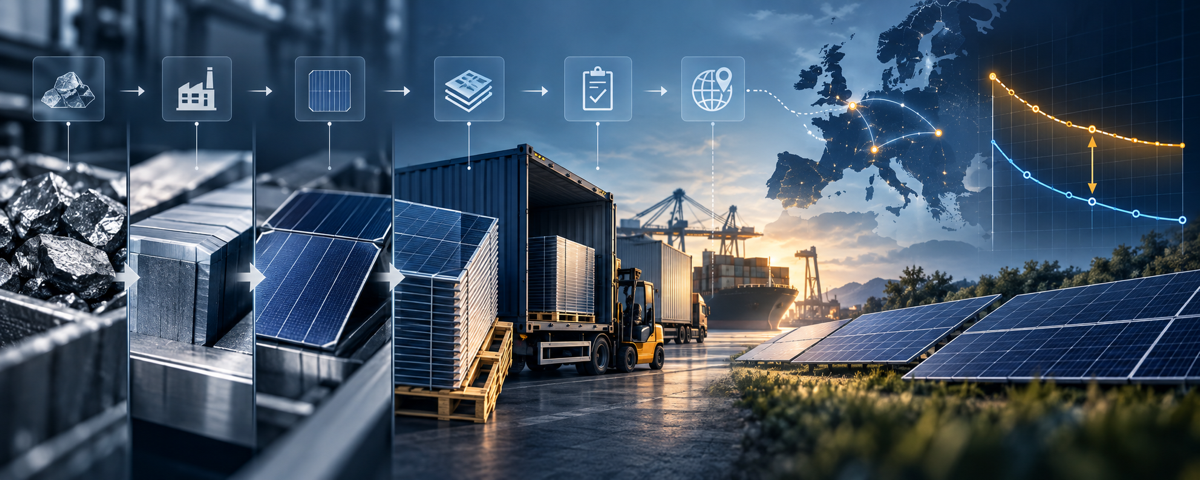
European procurement is splitting into two negotiations: evidence of origin and evidence of an executable delivered price.
3. Qualitas Energy’s proposed Cero acquisition concentrates a 5.8 GW European solar-and-storage platform
Qualitas Energy signed an agreement to acquire Cero Generation’s core European platform from Macquarie Group. The perimeter contains 5.8 GW of solar PV and battery projects across the United Kingdom, Italy and Spain: more than 2 GW is operating, under construction or ready to build, with another 3.8 GW in development. The local teams in London, Milan and Madrid are also included, and the business is expected to continue under the Cero name after closing. For suppliers, a platform transaction of this size creates a window for portfolio-wide specification reviews, framework agreements, approved-vendor rationalization and O&M standardization. It should be treated as a post-signing integration lead rather than a completed change of control until closing conditions are satisfied.
Event date: 7 September 2026 | Publication date: 7 September 2026 | Priority: Very high | Confidence: High on the signed agreement; completion remains conditional. Source
4. Romania’s Părău 1 hybrid project turns merchant-storage theory into an operating benchmark
Econergy has started commercial operations at a 70 MW / 141 MWh battery connected to its existing 92 MW Părău 1 solar plant, creating a 162 MW hybrid site. The battery can charge from the grid during low or negative-price periods as well as capture generation that would otherwise be clipped. Public reporting describes the EUR 85 million project as fully merchant and cites expected annual storage revenue of about EUR 9.7 million, with the company treating Părău 1 as a template for further hybridization. The useful insight is not the headline payback implied by one forecast; it is the operating architecture. Dedicated grid-import rights, dispatch optimization and co-location value can matter as much as cell cost.
Event date: 7–10 September 2026 | Publication date: 10 September 2026 | Priority: Very high | Confidence: High on capacity and status; medium on forward revenue. Source
Capital is moving toward platforms that can standardize procurement while carrying assets from acquisition through construction and operation.
5. A EUR 16 million bridge facility gives two Polish merchant BESS projects a route from acquisition to construction
Tavion secured a EUR 16 million revolving bridge facility for two ready-to-build standalone batteries in Poland with a combined capacity of 39 MW / 78 MWh. The facility includes acquisition and construction tranches and was structured on a fully merchant basis by a European debt fund. The structure shows that Poland’s storage market is beginning to support capital designed for speed between project purchase and longer-term construction financing, despite revenue uncertainty. Suppliers should bring bankable delivery milestones, lender-grade technical documentation and a clear interface between battery, PCS, EMS and market optimizer.
Event date: September 2026 | Publication date: 10 September 2026 | Priority: High | Confidence: High on financing and capacity; revenue remains market-dependent. Source
6. Switzerland’s largest operating battery site opens as Axpo builds more than 300 MW elsewhere in Europe
Axpo and energieUri inaugurated two batteries at the same Gurtnellen site with power ratings of 50 MW and 8.4 MW. Axpo says the combined location is currently Switzerland’s largest battery installation and will support renewable integration and grid stability. More important for forward sales, Axpo also reports more than 300 MW of additional battery projects under construction in France, Germany, Italy, Poland and Romania. The named pipeline creates potential demand for balance-of-plant equipment, monitoring, commissioning, spares and augmentation planning, but power capacity should not be converted into energy volume: neither duration nor MWh was disclosed.
Event date: 9 September 2026 | Publication date: 9 September 2026 | Priority: High | Confidence: High on power ratings and pipeline; duration was not stated. Source
Operating value depends on connection rights, control architecture and serviceability, not only installed battery power.
European sales opportunities
| Target accounts and markets | Product entry point | Recommended follow-up |
|---|---|---|
| EU public-tender and subsidized-project developers | Traceable module BOM, origin declarations and low-carbon evidence | Build an evidence matrix by component and factory; identify every claim that still requires verification |
| Cero platform and its UK, Italian and Spanish EPC/O&M ecosystem | Portfolio frameworks, standardized PV/BESS specifications, spares and multi-country service | Map assets by project stage and approach with a portfolio-standardization proposal after closing milestones are clear |
| Romania: Econergy and hybrid-project contractors | BESS, PCS/EMS integration, clipping recovery, grid-charging controls and augmentation | Request connection configuration, dispatch strategy, degradation limits and service scope before pricing |
| Poland: Tavion, lenders, technical advisers and EPC partners | Lender-ready two-hour BESS packages, interface control and commissioning documentation | Prepare a due-diligence pack covering grid code, fire strategy, guarantees, degradation and optimizer interfaces |
| Axpo’s six-market storage ecosystem | Electrical balance of plant, monitoring, spares, augmentation and long-term service | Offer a cross-market service matrix and confirm duration and awarded scopes project by project |
| Rotterdam, Portugal and Greece distribution channels | Format-specific TOPCon and BC stock with transparent delivered cost | Publish executable offers by SKU, warehouse, Incoterm and dispatch date instead of one blended price |
Risks and warnings
- Policy: the 50% European-content threshold is a proposal, not enacted law. Build readiness without presenting it as final.
- Pricing: manufacturer guidance can rise while completed deals remain flat; do not apply one percentage move to all formats.
- Compliance: local assembly does not automatically prove local component content. Unsupported origin claims can disqualify tenders.
- Transaction: the Cero acquisition is signed but not completed. Do not assume procurement authority or vendor lists have changed.
- Merchant revenue: stress-test spreads, degradation, market access and optimizer fees before extrapolating project forecasts.
- Competition: justify TOPCon and BC premiums through BOS savings, yield or constrained-area value.
- Supply chain: warehouse premiums only pay when stock, documentation, delivery and title transfer are verified.
- Data quality: MW is not MWh. Never infer storage duration where the sponsor has not disclosed it.
Brand and competitor dynamics
| Class | Public signal | Commercial meaning |
|---|---|---|
| lead | Qualitas Energy signed to acquire Cero’s 5.8 GW platform | Watch for portfolio-wide specification, framework-supply and O&M reviews after closing milestones |
| lead | Econergy started operation of the 70 MW / 141 MWh Părău 1 battery | Combine hardware with connection, dispatch, clipping-recovery and lifecycle assumptions |
| lead | Tavion funded two Polish merchant BESS assets totaling 39 MW / 78 MWh | Fast lender diligence and milestone certainty can outweigh an undifferentiated lowest-price bid |
| lead | Axpo reports more than 300 MW of batteries under construction in five European markets | Cross-market service, spares and commissioning consistency offer a regional entry point |
| question | EU local-content rules may reach 50% by 2036, but final methodology is unsettled | Prepare auditable evidence while avoiding unsupported eligibility claims |
| question | Module offers are firmer than many executable deals | Specify format, efficiency, stock, Incoterm, location and delivery week for every price claim |
No reliable public signal in this monitoring window justified a crisis, bug, praise or spam classification. No measured user-brand mention was identified.
Seven-day trend
Three reports dated 4, 9 and 11 September support a directional seven-day comparison. The baseline remains too short for statistical spike detection.
| Signal | Direction | Interpretation |
|---|---|---|
| Local-content and traceability pressure | New abnormal signal | Qualification is moving toward component-level origin and anti-circumvention evidence |
| Utility and merchant storage execution | Up | Romania reached operation, Poland funded ready-to-build projects and Switzerland commissioned its largest site |
| Platform consolidation | Up | The Cero transaction adds a portfolio-integration route to the financing trend |
| Module-price direction | Mixed | Cost-supported offers are firmer, but weak demand limits pass-through into signed deals |
| Counterparty risk | Still elevated | Payment security remains necessary even as capital concentrates around large platforms |
Coverage disclosure
- Measured: six distinct public developments from official company releases, an EU policy explainer and specialist market reporting. Priority is an editorial sales-value ranking, not measured popularity.
- Proxy: search-visible public pages and open trade reporting. X, Instagram, TikTok, LinkedIn, Xiaohongshu, WeChat, WeChat Channels and Douyin were not measured.
- User-provided: publishing cadence, English-only language, brand, topic and website-workflow requirements. No user-provided market figures were used.
Three immediate sales actions
- Build a tender-ready origin pack: map assembly, cell, wafer, glass, frame and critical component origins, with supporting evidence and a list of unverified claims.
- Replace blended price lists with executable stock offers: quote TOPCon, high-power and BC formats separately by warehouse, Incoterm, quantity, stock date and dispatch week.
- Open four account-specific campaigns: approach the Cero ecosystem with portfolio standardization, Econergy with hybrid replication, Tavion with a lender-ready two-hour BESS package, and Axpo’s contractors with multi-country spares and service.